Showing posts with label gold prices. Show all posts

Sunday, November 01, 2026

Three Markets, One Signal: How the PSEi, Peso and BVAL Priced Suppression in October


Price controls take some time for their flaws and distortions to develop: for the longer they last, the more do their controlled prices diverge from the prices that would be obtaining on the free market—Murray N. Rothbard 

In this issue: 

Three Markets, One Signal: How the PSEi, Peso and BVAL Priced Suppression in October

I. The PSEi’s “Rotation” Is the Cover Story

II. A Floor Is a Price Control

III. GCASH: The IPO With a Subsidy Bid Underneath

IV. “Don’t Panic” Is a Policy

V. The Yield Curve Takes No Orders

VI. Whac-a-Mole Economics

VII. Periphery to Core

VIII. What October Priced: The Cost of Suppressing Adjustment

VIII. Conclusion: October’s Cost of Suppressing Adjustment 

Three Markets, One Signal: How the PSEi, Peso and BVAL Priced Suppression in October 

Every intervention bought stability in one market and billed another. In October, the bill is showing up in bond yields and FX reserves as global liquidity drains from the outside 


I. The PSEi’s “Rotation” Is the Cover Story


Figure 1

The PSEi 30 ended October almost unchanged month on month (-0.02%). It is still down 6.16% year to date and 4.2% year on year. The headline hides a redistribution of index leadership. (Figure 1, table) 

ICTSI, the largest heavyweight, surrendered 89.54 gross points (-5.84%). The next four largest names (SM +7.84%, BDO +4.42%, BPI +1.08%, SMPH +10.34%) contributed 91.23 points and more than offset it. Breadth tilted positive at 18 advancers against 12 decliners. Yet heavier losses in SCC, DMC and CNPF dragged the simple average change across the 30 members to -0.66%. (Figure 1, middle image) 

The gap between -0.02% and -0.66% comes from free-float market-cap weighting. A handful of names decide the headline. After ICTSI’s drop, the five largest still command 55.24% of the index. (Figure 1, lowest graph) 


Figure 2 

The wider PSE tells the real story. 

Breadth was 1,811 advancers against 2,113 decliners, which extends broad-market selling to eight of the first ten months of 2026. (Figure 2, topmost pane) 

Main Board volume (MBV) rose 20.4% year on year to Php 129.67 billion, but cross transactions took 27.71% of it. (Figure 2, middle diagram) SM’s Php 8.736 billion block alone was about 24% of the month’s cross volume. 

ICTSI’s share of Main Board volume (MBV) climbed from 19% in September to 23.75% in October, while foreigners net sold about Php 1.3 billion of the stock as it fell. Local institutional buying absorbed the selling. (Figure 2, lowest chart) 

The index’s “stability” rests on an engineered domestic support for a heavyweight under foreign liquidation. 

II. A Floor Is a Price Control


Figure 3 

The top 10 brokers averaged 66.8% of daily MBV, and the top 10 issues averaged 72%. That concentration put an implicit floor near 5,600 under the PSEi all month. (Figure 3, topmost visual) 

A floor held by a few brokers and a few issues is a price control, whatever name it goes by. 

The PSEi is a free float market capitalization-weighted benchmark. It does not measure the breadth or health of the equity market. The media and the establishment treat it as if it did, though five issues decide most daily outcomes. Confusing the two is how benchmarkism disguises concentration as stability. 

Leadership rotated in October, but concentration did not go away. It only changed where the support was pointed. Extreme trading concentration, persistent negative breadth and thinning liquidity are the symptoms, and the distorted price signals they produce misallocate capital. 

Ironically, almost no one comments on it—as if it is a taboo. 

III. GCASH: The IPO With a Subsidy Bid Underneath 

The GCash listing offered another illustration of the market's dependence on concentrated liquidity. 

GCASH’s weekly share of Main Board volume fell from 34.9% to 9.22%. The stock swung -5% on the week of October 23 and +5.42% the following week. It closed at Php 6.61, a hair above the Php 6.60 offer price. The price is where it is because someone is buying it. (Figure 3, middle image) 

UBS, the sole stabilizing agent, bought 786.57 million shares at an average of Php 6.571 in the week ending October 23. That cost about Php 5.17 billion and used up 65% of its maximum stabilization buying capacity in the first trading week. The budget is the 1.204 billion overallotment shares, worth Php 7.95 billion at the offer price. That leaves about 417.5 million shares, roughly Php 2.75 billion. The support window runs about 30 days from the October 20 listing. There is no update on this as of October 30th. 

The mechanism is simple. The agent sells the overallotment shares short at the offer price, then buys them back in the open market to defend it. A bid sits just under Php 6.60 until the money runs out. It is the PSEi’s floor in miniature: a price held by a dedicated buyer and not by savings. 

An IPO can generate enormous turnover and retail participation without leaving behind durable secondary-market liquidity. The question is what happens when the support expires. 

IV. “Don’t Panic” Is a Policy 

The peso is the second signal. 

The peso touched Php 64.17 per dollar on October 27. That was its 33rd record low of 2026, the eighth in October, and the fifth consecutive record session from October 21 to 27. The President then said, “Don’t panic...we have defenses,” and USDPHP retreated to Php 63.74 by the week’s close. 

No leader makes that statement without his agencies behind it. It signals that the political leadership will do what it takes to “stabilize” the peso. The motive is to look stable. The policy is intervention. The effects arrive later… or in other prices. 

A managed retreat does not touch the cause, which is the savings-investment gap. Free-lunch politics and the policies behind it sustain spending beyond what the economy can finance from its own production. 

The USDPHP rose 1.76% in October, taking its gain to 8.42% year to date and 8.31% year on year. That was the second biggest monthly rise of 2026 after March’s 5.35% (from February's 57.665 to March's 60.748). (Figure 3, lowest diagram) 

The external side of the gap is tightening. OFW remittances, tourism, FDI and portfolio inflows have all weakened. BPO and AI-linked electronics exports help but cannot close the gap, and they carry their own exposure. 

A reversal in AI capital spending would move from global markets into Philippine export receipts and widen the deficit. 

Administered prices, regulatory relief, FX management and accommodative monetary measures have postponed the recognition of the imbalance. Postponement is not resolution. The pressure surfaces through other prices, balance sheets and markets. 

With the balance of payments (BoP) under record pressure and reserves falling, the BSP’s quasi-soft peg has given way to a low-volume, low-volatility crawl. The string of records is that adjustment showing up. 

The BSP still has “tools,” but none is free. It can run down reserves, lever up through repos and derivatives, monetize part of its gold, borrow more (via the National Governnment) or turn to trade and price controls. These extend the process, but none creates dollars, domestic savings or productive resources. 

September shows the cost. Gross international reserves fell from $104.846 billion to $99.494 billion, a $5.352 billion drop to a three-year low. 


Figure 4 

The BSP attributes it mainly to its net foreign exchange operations. The composition is the tell. Other Reserve Assets, the bucket that holds net derivative positions, repo assets and investment pools, fell from $15.471 billion to $9.985 billion, about $5.5 billion and 35% in one month. That is larger than the entire decline. Gold valuation took off another $1.287 billion. Total currency and deposits rose about $1.54 billion. The drain came from the derivative and repo positions behind the peso defense, not from the plain securities and deposits the headline suggests. (Figure 4, topmost image) 

The September BOP deficit was a record $3.144 billion, taking the year-to-date deficit to a historic $9.087 billion—which is just a hairline short of the DBCC’s revised 2026 target of US$9.2 billion (1.8 percent of GDP) with a quarter to go. Borrowed support can defer the adjustment. It cannot remove the financing constraint. (Figure 4, middle chart) 

V. The Yield Curve Takes No Orders 

The sovereign bond market supplied the third signal. 

The public watches the PSEi and the peso. It pays little attention to government bonds, and that is where the cost of financing the state shows up. 

More than anything else, these pressures are most clearly reflected in the interest rate environment, as evidenced by the Philippine Treasury's BVAL yield curve. 

The yield curve shifted upward across all tenors in October compared with September, with positive spreads and the largest increases concentrated in the belly of the curve—a bulge. (Figure 4, lowest chart) 

More importantly, from the one-year tenor onward, yields are at or near multi-year highs. Rising yields are the market’s way of repricing inflation, duration risk and the cost of financing the state. 

The fiscal connection is direct. Government borrowing competes with private investment for finite pools of savings. As financing needs rise, the state’s demand for funds presses against the resources available to businesses (and even banks) seeking capital for production and expansion. 

This is the crowding out effect—and it does not require a textbook interest-rate shock to operate. 

Financial repression adds another channel. Directed credit, captive institutional demand and policies that steer savings toward government or favored borrowers can suppress the visible cost of financing while displacing alternative uses of capital. The allocation changes even when the headline rate does not fully reveal the pressure. 

The result is a distorted investment process: financing follows political and institutional priorities rather than the unrestrained signals of market prices, risk and expected returns. 

The rising yield curve is the market pushing back against that arrangement. Government can influence the terms under which savings are mobilized. It cannot command away scarcity.


Figure 5 

Equities hide the weakness through benchmark concentration. The peso absorbs external pressure through intervention. Bonds reprice the cost of the state. As evidence, the Philippine 10-year Treasury yield has climbed to multi-year highs even as the PSEi tests its 2025 lows (Figure 5, topmost window) 

Three markets, one imbalance. 

VI. Whac-a-Mole Economics 

This is the intervention spiral I call Whac-a-Mole Economics. Support the PSEi and the pressure moves to the peso and bonds. Lean on the peso and the valve opens in equities and bonds. Suppress one price and the imbalance resurfaces in another. 

The mechanism is not mysterious. Prices coordinate competing claims over scarce resources. Interfering with their adjustment does not remove the scarcity. It changes where the pressure builds, who absorbs it and when the cost becomes visible. 

The price signal is not the disease. It is the information that reveals scarcity. Suppress the signal and the distortion grows while its symptoms migrate across markets and time. 

VII. Periphery to Core 

The Philippines is not alone in this. 

The magnified paroxysm across several equity benchmarks—the Indonesian JKSE, Korea’s AI-heavy KOSPI, and, more recently, Brazil’s Bovespa—exhibits a common denominator.  (Figure 5, middle visual) 

As an aside, in Brazil, Lula's reelection triggered a rout in Brazilian stocks, deepening an already prolonged contraction in Latin America's equity-fund industry, where more than 400 equity funds have disappeared and IPO activity has stalled. (Figure 5, lowest image) 

Yet each crash has a local headline, whether politics or AI, but they share the global liquidity cycle. 

The crashes did not need to arrive on the same day to demonstrate this. Peaks came at different points in the year, and the common condition is liquidity withdrawal. 

I call this periphery-to-core transmission. 

Withdrawal first exposes the weakest links: the markets, sectors, and balance sheets most dependent on cheap financing, leverage, and steady inflows. Rising yields then collide with accumulated malinvestments and balance-sheet mismatches. The war economy, supply disruptions, incumbent monetary policies, and fiscal conditions add further pressure.


Figure 6 

Even gold has become an ATM for liquidity-strapped investors. Its sharp declines alongside Bitcoin reflect forced liquidation and the demand for cash, not a change in its long-term monetary role. (Figure 6, upper chart) 

The core is now under pressure. This week’s AI dumpfest hit the Nasdaq Composite with a 2.0% weekly loss, its third consecutive weekly decline, and a 7.04% slide over three weeks. Friday’s 2.9% drop was its largest one-day percentage decline since June 5, following disappointing results from Intel and Amazon. 

Meanwhile, hyperscalers are financing build-outs in debt markets, adding leverage to an already capital-intensive cycle. AI off balance sheet commitments hits $4.1 trillion: Up 1 trillion in 90 days.  (Figure 6, lower graph) 

When the cost of capital rises, the expected returns on long-duration investments become harder to justify. What starts as an equity repricing can migrate into corporate credit, debt servicing, and investment spending. 

The danger is contagion: falling asset prices, tighter financing, forced deleveraging, and contracting credit. A global recession is the risk embedded in this process, and a broader debt crisis is becoming highly probable. 

The periphery is not insulated from the core, and the core is not immune to the financing constraints already visible at the periphery. 

VIII. Conclusion: October’s Cost of Suppressing Adjustment 

Free lunch politics is NEVER FREE. 

The PSEi is held up by the five biggest market caps, a persistent concentrated broker bid and a stabilizing agent for GCASH. 

The peso crawls to records while the BSP burns reserves and the President says don’t panic.

Yields rise from the one-year tenor outward to multi-year highs. 

The motive behind each intervention is the same: to show stability before the financing gap is closed. The policy is price support, administered relief and reserve burn. The effect is that pressure moves to the next price. Postponement has a cost, and the cost compounds. 

Almost everyone has been programmed to believe that spending drives the economy. Spending is the visible half. Before anyone can spend, someone has to have made something others want: a harvest, a service, a product, an export. A fisherman buys rice with the fish he sold. Money is the claim ticket, and the claim is worth only what stands behind it. What you can buy is set by what you or others produced. Or imagine booking a vacation at a resort on the Moon. There may be demand, but there is no supply. 

So printed money, borrowed money and extended credit can raise spending today. They cannot create the rice, or the dollars, that the spending needs to meet. They only change who gets the existing output and push the bill onto future output. 

That is why the pressure shows up where it does. Dollars come from selling something to the world. Savings come from producing more than you consume. When spending commitments outrun both, the gap appears as a record BOP deficit, a weaker peso and higher yields, because savings are scarce and the state is bidding for them. 

A stock, a peso and a bond are all claims on real output and real savings. A floor can hold a quote, but it cannot create the output behind the claim. Indices, GDP and gross savings add up claims into one number and hide who actually produces and who just holds paper. That is the difference between accounting stability and economic resilience. 

The three markets are not telling three different stories. In October, they converged on one signal: the growing cost of suppressing adjustment. Support the PSEi and the pressure shows up in the peso. Lean on the peso and it shows up in the bond curve. 

Close one valve in a system under rising pressure and the pressure does not disappear. It finds the weakest seam. In October, the seams were the PSE’s market internals, the peso and the bond curve. 

The next one may not be in Philippines’ hands at all. Global liquidity is draining, and the pressure is now being fed from outside.


Monday, April 28, 2025

Why the Philippine Peso's Strength Masks Underlying Vulnerabilities


If the governments devalue the currency in order to betray all creditors, you politely call this procedure 'inflation'--George Bernard Shaw 

In this issue

Why the Philippine Peso's Strength Masks Underlying Vulnerabilities

I. Philippine Peso in the Face of a Weak Dollar

II. Is the Peso’s Strength Rooted in Fundamentals? Portfolio Flows: A Mixed Picture

III. Remittances: Diminishing Returns

IV. Tourism: Geopolitical Headwinds

V. Trade Data: Structural Deficiencies Revealed

VI. Balance of Payments and Gross International Reserves: A Fragile Façade (Boosted by Borrowings)

VII. BSP’s Tightening Grip on FX Markets and the Illusion of Stability

VIII. The Speculative Role of the BSP: Other Reserve Assets

IX. Rising External Debt: A Ticking Time Bomb

X. Conclusion: Transitory Strength, Structural Fragility 

Why the Philippine Peso's Strength Masks Underlying Vulnerabilities 

A strong Philippine peso hides the cracks of FX debt, deficits, and interventions.

I. Philippine Peso in the Face of a Weak Dollar 


Figure 1

Surprisingly, the Philippine peso has outperformed its regional peers. Year-to-date, the USD-Philippine peso USDPHP has declined by 2.73% as of April 25. (Figure 1, upper window) 

Despite a generally weak dollar environment, the greenback has risen against some ASEAN currencies: it has appreciated by 4.32% against the Indonesian rupiah (IDR) according to Bloomberg data, and by 2.2% against the Vietnamese dong (VND) based on TradingEconomics data, year-to-date. 

The USDPHP’s behavior has largely mirrored the oscillations of the USD-euro $USDEUR pair and the Dollar Index $DXY, both of which have declined by -9.5% and -9% YTD, respectively. The euro commands the largest weight in the DXY basket at 57.6%, amplifying its influence over the index's performance. (Figure 1, lower image) 

II. Is the Peso’s Strength Rooted in Fundamentals? Portfolio Flows: A Mixed Picture  


Figure 2

Foreign portfolio flows have been volatile. 

The first two months of 2025 recorded a modest net inflow of USD 176.6 million, following significant outflows of USD 283.7 million in January and inflows of USD 460.34 million in February. These inflows were mainly directed towards government securities (USD 366 million), while the Philippine Stock Exchange (PSE) suffered USD 189 million in outflows. (Figure 2 topmost graph) 

In 2024, Philippine capital markets saw foreign portfolio inflows of USD 2.1 billion—the largest since 2013—suggesting a temporary vote of confidence, albeit in a risk-on environment favoring emerging markets more broadly. 

Meanwhile, the Bangko Sentral ng Pilipinas (BSP) reported that foreign direct investment (FDI) flows fell 20% year-on-year to USD 731 million in January 2025 from USD 914 million the year prior. (Figure 2, middle chart) 

Still, 71% of January’s FDI consisted of debt inflows, rather than equity investments. 

Ironically, despite the administration's aggressive international junkets (2022-2024) aimed at wooing investors through geopolitical alliances, these efforts have borne little fruit. 

What happened? 

As previously noted, an overvalued peso—maintained by a de facto USDPHP soft peg—along with high "hurdle rates" stemming from bureaucratic red tape and regulatory barriers, and the implicit consequences of "trickle-down" easy money policies benefiting the government and their elites (i.e., crony capitalism), have collectively undermined Philippine competitiveness. 

III. Remittances: Diminishing Returns 

Overseas Filipino Worker (OFW) remittance flows continue to grow, but at a marginal and slowing pace. Personal remittances rose 2.6% in February, with cumulative year-to-date growth at 2.7%. (Figure 2, lowest visual) 

However, the long-term trend in remittance growth has been declining since its 2013 peak—a period that coincided with the secular bottoming of the USDPHP. 

This trend reflects the diminishing marginal impact of remittances on the peso’s valuation. 

In short, remittances are becoming less material in influencing the peso’s foreign exchange rate. 

A more sustainable strategy would be to foster structurally inclusive economic growth—creating more high-quality domestic jobs and raising incomes—to reduce the country’s dependence on labor exportation and mitigate brain drain. 

Sadly, the slowdown in remittance growth does not point toward such an outcome. 

IV. Tourism: Geopolitical Headwinds


Figure 3 

The Philippine tourism sector's recovery may have stumbled. 

Foreign tourist arrivals fell by 2.42% in Q1 2025, while total arrivals—including overseas Filipino visitors—dropped by 0.51%. This was largely driven by a staggering 28.8% collapse in Chinese tourist arrivals in March and a 33.7% year-on-year plunge in Q1. This slump mirrors the escalating geopolitical tensions between the Philippines and China, particularly as Manila increasingly aligns itself with U.S. strategic interests. (Figure 3, upper diagram) 

Interestingly, American tourist arrivals also fell by 0.7% in March, although they rose by 7.9% for Q1 overall. Nonetheless, the growth in American tourists has hardly offset the sharp loss of Chinese visitors. (Figure 3, lower chart) 

In effect, a ‘war economy’ reduces the Philippines’ attractiveness as a tourism and investment destination. 

V. Trade Data: Structural Deficiencies Revealed


Figure 4

The Philippines' trade deficit narrowed by 11.44% to USD 3.16 billion in February, owing to a 1.8% contraction in imports and a muted 3.94% increase in exports, year-on-year. (Figure 4, upper graph)

While many mainstream talking heads argue that tariff liberalization will eventually benefit the Philippines, external trade figures tell a different story—one marred by structural weaknesses: high energy costs, a persistent credit financed savings-investment gap (a byproduct of trickle-down policies), the USDPHP peg, human capital limitations, economic centralization, regulatory hurdles and more.

Since 2013, total external trade (imports + exports) has grown at a CAGR of 4.84%—driven by imports growing at 5.95%, compared to exports at only 3.42%. Adjusted for currency movement (with the USDPHP CAGR at 3.01%), this yields a real export CAGR of just 0.41% versus 2.85% for imports, implying a real external trade CAGR of only 1.77%. (Figure 4 lower image)

While rising imports may superficially suggest robust consumption, a deeper question emerges: Is consumption fueled by genuine productivity gains—or by unsustainable credit expansion?

Ultimately, the data show that import-driven consumption has widened the trade deficit, and that local manufacturing remains largely uncompetitive relative to regional peers.

Against this backdrop, how realistic is it to expect that Trump's proposed tariffs will magically turn the Philippines into an export hub?

VI. Balance of Payments and Gross International Reserves: A Fragile Façade (Boosted by Borrowings)


Figure 5

The BSP reported a Balance of Payments (BoP) deficit of USD 2 billion for March 2025, following a staggering USD 4.1 billion deficit in January—an 11-year high—and a temporary surplus of USD 3.1 billion in February. The Q1 2025 BoP deficit stood at USD 2.96 billion. (Figure 5, upper window)

The BSP attributed these outflows to "drawdowns on reserves to meet external debt obligations" and to fund foreign exchange operations—justifications previously offered for January’s record deficit.

Meanwhile, February’s surplus largely stemmed from net foreign currency deposits by the National Government, sourced from proceeds of ROP Global Bond issuances and income from BSP’s foreign investments—in other words, from external borrowings.

Notably, the BSP has admitted that the year-to-date BoP deficit mainly reflects the widening goods trade deficit. Either this conflicts with PSA trade data showing a narrowing February deficit, or it hints at a possible sharp deterioration in March's trade balance.

Regardless, the BoP reports clearly indicate heavy BSP intervention in the FX market, even though the USDPHP remains well below the 59-level psychological ceiling.

Consequently, the BSP’s gross international reserves (GIR) dropped from USD 107.4 billion in February to USD 106.7 billion in March—a USD 725 million decline. (Figure 5, lower diagram)

Importantly, much of the GIR’s support comes from the government’s external borrowings deposited with the BSP. Thus, the GIR has been padded up artificially.


Figure 6

Even more striking: gold’s record high prices have prevented a steeper GIR decline, despite the BSP selling small amounts of gold in February.  

Gold's share of GIR slipped marginally from 11.4% in February to 11.22% in March. (Figure 6, upper pane)

Had it not been for ATH (all-time high) gold prices, the GIR would have deteriorated more significantly. 

As previously explained, as with the 2020 episode, sharply falling gold inventories preceded the devaluation of the peso. (Figure 6, lower chart) 

Outside of gold, a large share of GIR now constitutes "borrowed reserves"—a growing vulnerability tied directly to the BSP’s soft peg strategy for the USDPHP. 

This suggests that the recent GIR stability could be masking underlying vulnerabilities.

VII. BSP’s Tightening Grip on FX Markets and the Illusion of Stability 

It is therefore almost amusing to encounter this news item, based on the BSP’s publication: 

Inquirer.net, April 24: "The Bangko Sentral ng Pilipinas (BSP) tightened regulations on foreign exchange (FX) derivatives involving the Philippine peso to ensure these are not used for currency speculation. Circular No. 1212, signed by Governor Eli Remolona Jr., mandates that banks authorized to transact in non-deliverable FX derivatives must ensure these are used for legitimate economic purposes." 

But who are the likely participants in FX swaps, non-deliverable forwards, and FX derivatives?

Not me. Not the general public. 

Given that PSE participation is only around 1% of the total population (as of 2023), the obvious answer is: banks and their elite clientele—the BSP’s own cartel members. 

Thus, what is the real message behind this announcement? 

First, banks and their elite clients may have been positioning against the peso, in ways inconsistent with BSP policy—prompting the BSP to tighten currency controls. 

Second, the BSP wants to show the public it is taking action, even as real risks accumulate. 

Third, something is amiss if the BSP feels compelled to impose tighter controls even with the USDPHP hovering at 56—well away from their upper band limit. 

Ultimately, who is truly engaged in currency speculation here? 

VIII. The Speculative Role of the BSP: Other Reserve Assets


Figure 7

Since 2018, the BSP has increasingly used Other Reserve Assets (ORA) to manage its GIR. (Figure 7) 

According to IMF IRFCL guidelines, ORA includes:

-Net, marked-to-market value of financial derivatives (forwards, futures, swaps, options)

-Short-term foreign currency loans

-Long-term loans to IMF trust accounts

-Other liquid foreign currency financial assets

-Repo assets 

The BSP’s ORA surged by 210.3% in February, lifting its share of GIR to 9.18%. Yet, even this rise was overshadowed by gold's role in preserving GIR totals. 

In truth, the BSP itself is a speculator—aggressively managing USDPHP levels against market forces. 

In pursuing short-term stability, it risks building imbalances that will eventually unwind with greater force. 

This has been evident in the widening BoP deficit, the rising share of "borrowed reserves," and the sustained gold sales. 

IX. Rising External Debt: A Ticking Time Bomb


Figure 8

Perhaps most revealing is this BSP announcement: 

BSP, April 25, 2025: "The Monetary Board approved USD 6.29 billion worth of proposed public sector foreign borrowings in Q1 2025, up by 118.91% from USD 2.87 billion during the same period last year." (bold mine) [figure 8, upper graph] 

Whatever the justification—whether for infrastructure, green (climate), defense, or welfare or others—debt is debt. 

Even though the BSP paid down nearly half its obligations (posting a Q1 BoP deficit of USD 2.96 billion), the residual balance should add to the swelling external debt stock. (Figure 8, lower chart) 

Recall that as of Q4 2024, government debt already accounted for 58% of total external debt. Banks and non-finance institutions are likely to add to this pile. 

Higher public debt implies higher future debt servicing costs, crowding out resources from productive investments, draining savings, increasing leverage, and deepening the Philippines’ dependence on foreign financing. 

X. Conclusion: Transitory Strength, Structural Fragility 

The Philippine peso’s strength in 2025, buoyed by a weak U.S. dollar, masks underlying vulnerabilities. Structural issues—overvalued currency, uncompetitive manufacturing, declining remittance growth, geopolitical strains, and reliance on borrowed reserves—undermine long-term stability. 

Through the USDPHP soft peg, the BSP’s interventions, while stabilizing the peso in the short term, foster imbalances that could unravel with a global tightening of monetary conditions. 

Without addressing these structural challenges through inclusive growth, deregulation, and reduced dependence on debt and remittances, the Philippines risks a rude awakening. The peso’s current resilience is less a reflection of economic strength and more a temporary reprieve, vulnerable to shifts in global financial tides. 

Nota bene: Although we discussed tourism and remittances, we did not cover business process outsourcing (BPO) and other export services in depth, largely due to limited data and the need to rely on GDP proxies. Regardless, surging debt levels are exposing widening FX liquidity vulnerabilities that services alone cannot offset. 

____

reference 

IMF INTERNATIONAL RESERVES AND FOREIGN CURRENCY LIQUIDITY GUIDELINES FOR A DATA TEMPLATE 2. OFFICIAL RESERVE ASSETS AND OTHER FOREIGN CURRENCY ASSETS (APPROXIMATE MARKET VALUE): SECTION I OF THE RESERVES DATA TEMPLATE, p.25 IMF.org


Sunday, April 27, 2025

April 7: The Day Global Risk Assets Bottomed: A Synchronized Reversal Across Stocks, Crypto, and Commodities


The conventional view serves to protect us from the painful job of thinking—John Kenneth Galbraith 

April 7: The Day Global Risk Assets Bottomed: A Synchronized Reversal Across Stocks, Crypto, and Commodities 

Following the April 7-8 lows, a synchronized rally swept across US, Asian or global stocks, commodities, and Bitcoin. Forget domestic interventions—this was a liquidity-driven comeback, sparked by global catalysts and market dynamics. 

I. Introduction 

On April 7-8, 2025, global markets teetered on the edge: Hong Kong’s Hang Seng cratered 13%, U.S. stocks wobbled, copper plunged 8%, and Bitcoin hit a yearly low. Fear ruled, with the VIX spiking to 46.98. 

Then, everything reversed course and headed higher through the next few weeks. 

From Tokyo to New York, stocks soared. Gold, oil, copper, and even Bitcoin joined the party. 

What sparked this global comeback? 

It wasn’t Chinese state buying or local policies. It was a liquidity tsunami, fueled by a massive global short-covering and capital rushing back to oversold assets. 

II. The Panic and the Spark


Figure 1

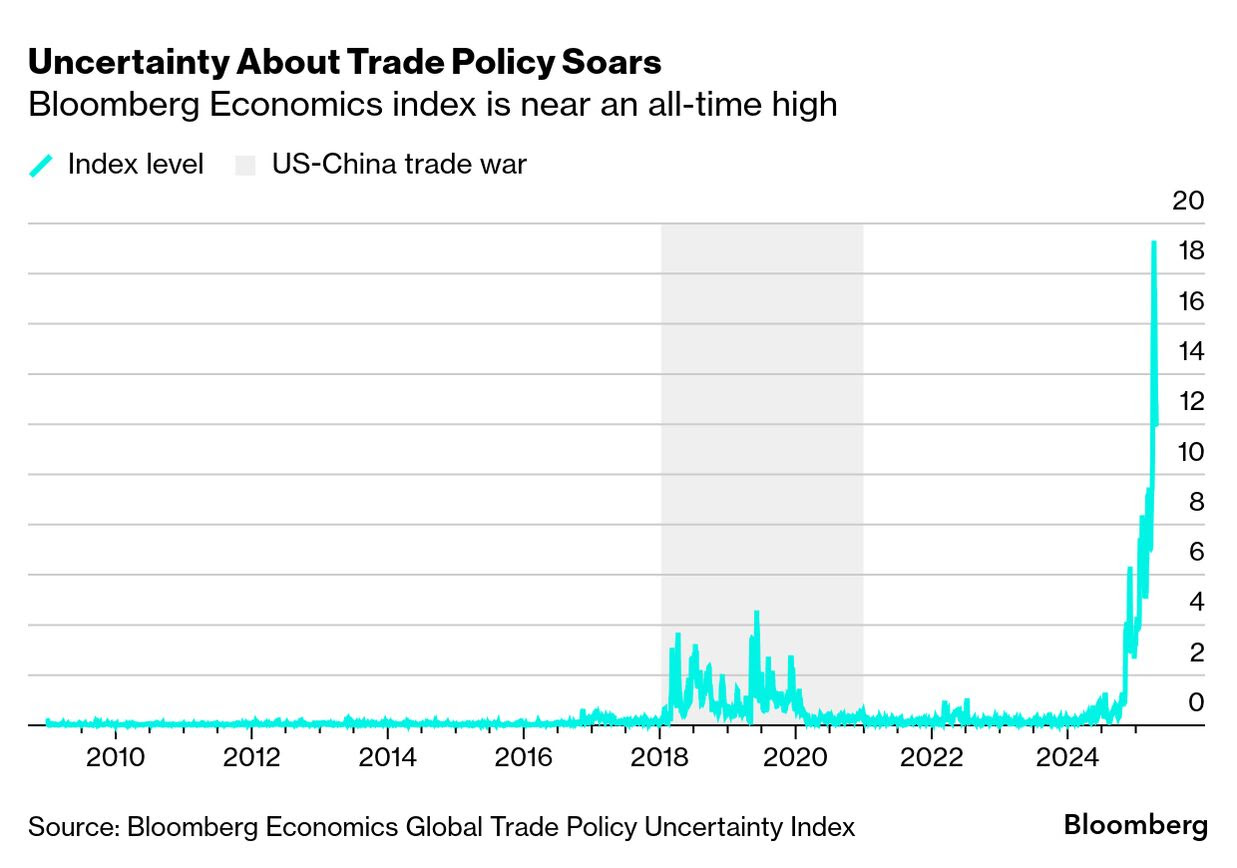
Concerns over the festering trade war, all-time high uncertainties, mounting geopolitical tensions in the face of a weakening global economy, and high systemic leverage put pressure on risk assets.   

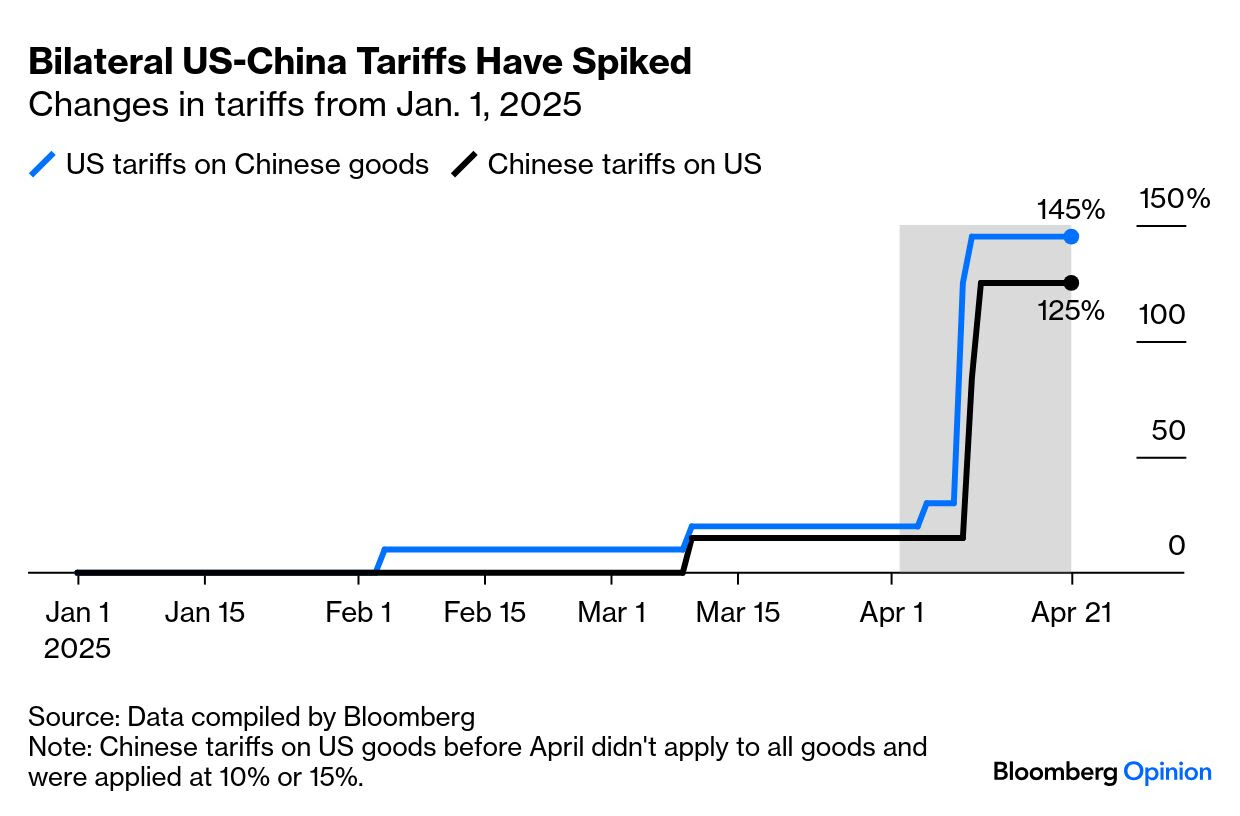
In charts, US-China bilateral tariffs soared in April.  (Figure 1)


Figure 2

The world’s government debt-to-GDP ratio remains high and is expected to rise further. (Figure 2, upper diagram) 

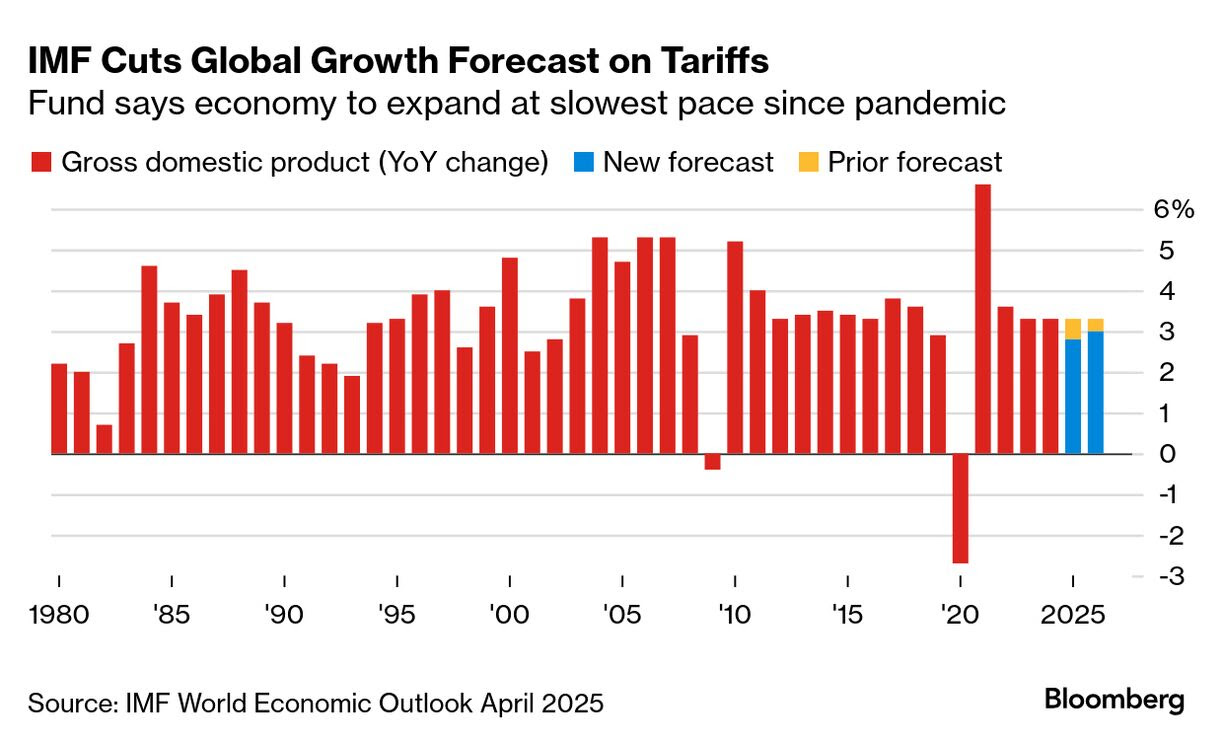
The IMF slashed its global GDP forecast from 3.3% to 2.8% in 2025 (Figure 2, lower image) 

Deflating prices, deleveraging, and liquidity tightening led to a risk aversion in global stocks, which culminated in April 7’s brutal selloffs. 

The Chinese yuan fell, or the US dollar-yuan USDCNY spiked, driven by China’s retaliatory tariffs. 

But late on April 7, rumors of a 90-day U.S. tariff pause (excluding China) surfaced, sparking a wild U.S. market swing (S&P 500 from -4.7% to +3.4%). 

Though denied, these rumors set the stage for April 8. 

III. April 8 Onwards: A Liquidity-Fueled Macro Short-Covering Rally 

On April 8, the selloff in some of the global markets had eased, and some had started a sharp recovery. 

Liquidity—fueled by institutional buying, short covering, and algorithmic trading—revived risk-ON sentiment.


Figure 3 

From the April 7-8 lows, the S&P Global Equity Index rebounded 11.2%, the US S&P 11.02%, and the Euro Stoxx 600 10.8% as of April 25th. (Figure 3, topmost pane) 

In Asia, China’s Shanghai Composite rallied 6.6%, while Hong Kong’s Hang Seng 50 surged 9.9%. (Figure 3, middle graph) 

Meanwhile, Southeast Asian bourses staged a massive recoil. Indonesia’s JCI surged 12.7%, Thailand’s SET 9.33%, and the Philippine PSEi 30 8.74%, over the same period. (Figure 3, lowest chart)


Figure 4

Strikingly, USD gold prices soared 12.1%, copper 20.2%, WTI crude 6.9%, and Brent crude 7.5% (Figure 4, upper window) 

The CRB Commodity Index advanced by 7.2%, while Bitcoin roared 28%. (Figure 4, lower visual) 

Risk-ON was suddenly back! 

The USDCNY spike U-turned and plunged, with China’s central bank selling dollars to slow the yuan’s fall, but this was secondary. (Figure 4, lower graph) 

I called this on my X.com post, "A macro short-covering rally." 

IV. Extreme Oversold Conditions 


Figure 5

The VIX nearly hitting 50 was a sign of extreme oversold conditions. Historically, this has proved to be a turning point. (Figure 5, upper chart) 

While past performance doesn’t guarantee future results, one thing is clear: liquidity re-emerged following oversold conditions, and the VIX metric may have been somehow validated. 

V. Why Liquidity, Not Local Policies 

Chinese state buying, PBOC intervention, and the BOJ’s yen-defense rhetoric were possibly too small to reinvigorate the world’s risk appetite. 

Yet, the rally’s timing, scale, and breadth—spanning stocks, commodities, crypto, and the yuan—points to a global liquidity flood, driven by tariff relief hopes, the Fed’s dovish narrative, and oversold conditions. 

VI. Takeaways: A Fragile Rally in a Fractured World 

Trump’s arbitrary and capricious policies (Tariffs or not) should sustain an ambiance of "regime uncertainty," which clouds economic calculation for the global economy. 

This is aside from geopolitical (e.g., latest India-Pakistan clash over Kashmir, the ongoing Israel-Palestine War, Russia-Ukraine War, US/Israel-Houthi War, frictions at South China Sea and Taiwan, et al.) and geoeconomic (US-China trade war) tensions. 

Trump’s backsliding against China has prompted Chinese media to make a mockery of his policies, which in the coming days could test his mercurial temperament. Rising markets may reanimate his belligerent trade and foreign policy stance. 

With Return on Investment (RoI) and "hurdle rates" indeterminate, investments will likely stall.  The financial world will likely chase short-term gains via the financial markets, which likely implies heightened volatility in the days to come. 

Easily, this ties to bear market rallies in stocks, which are often sharp and swift but fleeting. 

Furthermore, for a financial world increasingly dependent on central bank easy-money bailouts, mounting de-globalization dynamics, rising geopolitical and geoeconomic uncertainties, increasing risks of economic discoordination and disruptions, increasing leverage, volatile liquidity conditions, and escalating risks of stagflation will likely inhibit central banks from their traditional approach—all of which may reduce the likelihood of fuel for a financial market "blowoff." 

Lastly, aside from gold, central banks and governments have lately been amassing Treasury Bills—a sign of a stampede for liquidity. The last time they hit this high was during the Great Recession (2007-2009). They surpassed the highs during the 2020 pandemic recession. (Figure 5, lower chart) 

All told, all-time high gold prices plus the second-highest official inflows to Treasury bills are likely signs of a coming global recession or a financial crisis.


Sunday, March 30, 2025

Do Gold’s Historic Highs Predict a Coming Crisis?


Massive money printing and debt accumulation have gone on for something like 80 years, and the system has held together. Why should it end now? Maybe they can wring one more cycle out of the corrupt Keynesian system. That said, I think we have finally reached the actual crisis point. Although this certainly isn’t the first time the inevitable seemed imminent…—Doug Casey 

This three-part series sheds light on the multifaceted story of gold: 

Part one examines how gold price surges have predicted global crises, from the GFC to today. 

Part two analyzes the role of central banks in driving these record highs. 

Part three assesses how these highs could impact the shares of listed Philippine gold mining companies. 

In this issue

Do Gold’s Historic Highs Predict a Coming Crisis?

I. Gold at All-Time Highs: A Beacon of Crisis or Recession Ahead?

II. Gold, The Philippines and the Pandemic Recession:

III. The Bigger Picture: Gold as a Recession or Crisis Bellwether

IV. Gold Outshines the S&P 500: Gold’s Crisis Predictive Power in Focus

Do Gold’s Historic Highs Predict a Coming Crisis? 

First series on gold: Surging USD Gold Prices: A Predictor of Crises from GFC to Pandemic—What’s Next? 

I. Gold at All-Time Highs: A Beacon of Crisis or Recession Ahead?


Figure 1

Is the recent record-breaking streak of gold prices signaling an impending global recession or crisis? 

The relationship between gold and the US GDP has undergone a profound transformation. 

Ironically, gold’s multi-year climb began during the dotcom recession. It surged ahead of the Great Recession of 2007-2009—or 2008 Financial Crisis—and, while falling during its culmination, gained momentum once again before the climax of the Euro crisis. (Figure 1, upper and lower charts) 

Between May 2001 and September 2011, gold prices soared approximately 6.9 times, from $270 to $1,873. 

Thanks to interventions from central banks like the Federal Reserve (FED) and the European Central Bank (ECB), as well as their global counterparts, volatility subsided, and risk perception diminished, ushering in a “goldilocks” period. During this time, gold prices retraced roughly 43%, falling to $1,060 by December 2015. 

However, China’s unexpected currency devaluation in August 2015 triggered a stock market crash lasting until February 2016, further compounded by Donald Trump’s election, ignited the next leg of gold’s bull market, as investors once again sought refuge in the precious metal. 

Gold reached new heights during the US repo crisis of 2019, continuing its ascent prior to the onset of the global pandemic recession. 

It achieved an interim peak of $2,049 in August 2020, representing a remarkable 93.33% increase from its low in 2015. 

Despite the outbreak of the Russia-Ukraine war in February 2022 and peak inflation in mid-2022, gold prices slid by 20%, hitting a low of $1,628 in September 2022. 

The Bank of England’s bailout of UK pension funds during the Truss budget crisis in October 2022 provided support or put a floor under gold prices, stabilizing the market. 

More recently, geopolitical conflicts—including the Israel-Palestine war and its extension to the Israel-Hezbollah conflict—along with rising tensions in hotspots like the South China Sea, escalating global protectionism, and the increased weaponization of finance, have fueled uncertainty. 

Additionally, the re-election of Donald Trump in 2024 and his administration’s policies, including trade wars, demands for the annexation/acquisition of Greenland, and control over the Panama Canal, have added to global economic and geopolitical instability. 

The resumption of hostilities in the Middle East, particularly Israeli attacks in Gaza and Beirut following a broken ceasefire, has further destabilized the region. 

In the Russia-Ukraine conflict, the UK and France have threatened to send troops to support Kyiv, risking escalation as Trump pushes for a quick resolution with concessions to Russia.

On April 2, 2025, Trump’s administration imposed 25% tariffs on all imported cars and light trucks, effective April 3, with plans for broader “reciprocal tariffs” targeting countries like Canada, Mexico, and the EU, prompting threats of retaliation and fears of a global trade war.


Figure 2

The ongoing trade war, did not emerge in a vacuum; rather, it reflects a broader, underlying trend of deglobalization. The rising number of import curbs—spanning tariffs, antidumping duties, import quotas, and other restrictions—represents the cumulative anti-trade measures undertaken by global authorities. 

According to Global Trade Alert, the number of import curbs in force among major economies, including the U.S., EU, China, Canada, Mexico, and the rest of the G20, has surged from under 1,000 in 2008 to over 4,000 by 2024 (Biden era), with the U.S. and EU leading the increase. (Figure 2) 

This proliferation of trade barriers has not only strained economic ties but also influenced foreign relations, contributing to a slippery slope of deglobalization that has materially heightened geopolitical stress. 

For instance, the U.S.’s aggressive tariff policies have prompted retaliatory measures from trading partners, fracturing alliances and fostering and deepening a climate of mistrust, which in turn exacerbates conflicts in regions like the South China Sea and Ukraine. 

This deglobalization trend, coupled with geopolitical flashpoints, has driven investors to seek safe-haven assets like gold, pushing prices to new all-time highs, as shown in the earlier chart, where NYMEX gold futures prices have spiked since 2023 even as the U.S. nominal GDP share of global GDP remains flat. 

II. Gold, The Philippines and the Pandemic Recession

Back in February 2020, I warned: 

In an interview with Ms. Gillian Tett at Council of Foreign Relations (CFR) on October 2014, former Fed chief Alan Greenspan aptly remarked: 

Remember what we're looking at. Gold is a currency. It is still, by all evidence, a premier currency, where no fiat currency, including the dollar, can match it. And so that the issue is if you are looking at the question of turmoil, you’ll find as we always find in the past, it moves into the gold price. 

The bottom line: Gold's uprising against central banking fiat currencies warn that the world is in the transition of entering the eye of the financial-economic hurricane! (Prudent Investor Newsletter)

It turned out that a global recession had already begun. 

In the Philippines, the first local COVID-19 case was reported in early March 2020, prompting the Duterte administration to impose a Luzon-wide lockdown, officially termed "Enhanced Community Quarantine." 

The Philippine economy subsequently plunged into a recession, with GDP contracting from Q1 2020 to Q1 2021.


Figure 3

Gold in the priced in the Philippine peso also soared ahead of the pandemic crisis. (Figure 3) 

III. The Bigger Picture: Gold as a Recession or Crisis Bellwether 

The charts illustrate a clear pattern: since the "Fed Put" during the dotcom bubble, gold’s record-breaking runs have consistently foreshadowed major recessions, economic crises, and geopolitical upheavals. 

These include the GFC, the Eurozone debt crisis, the U.S. repo crisis, the global pandemic recession, and the recent wave of conflicts and protectionist policies. Gold has also proven responsive to the serial interventions of central banks and governments, which have deployed easy money regimes and fiscal stimulus to mitigate these crises. 

For instance, the chart highlights how gold prices dipped during periods of perceived stability (e.g., post-2011 Euro crisis) but surged ahead of crises, reflecting its role as a leading indicator of economic distress. 

Is gold’s series of epic all-time highs yet another chapter in this unfolding saga of economic and geopolitical turmoil? The historical correlation between gold price surges and impending crises suggests that investors should remain vigilant 

IV. Gold Outshines the S&P 500: Gold’s Crisis Predictive Power in Focus


Figure 4

Finally, the mainstream financial narrative often compares gold’s performance to that of the stock market, framing gold as a speculative asset. In this context, gold has significantly outperformed the U.S. S&P 500 by a substantial margin over the past century, particularly since 2000.

However, this comparison is somewhat of an apples-to-oranges exercise. Gold, as a safe-haven asset, serves a fundamentally different role than equities, which are driven by corporate earnings, economic growth, and investor sentiment.

Gold’s value is tied to its scarcity, historical role as money, and its appeal during times of uncertainty, whereas the S&P 500 reflects the performance of the U.S. economy’s largest companies.

Despite this distinction, the comparison underscores gold’s resilience and appeal in an era marked by economic and geopolitical turbulence.

For a more nuanced perspective, the chart’s lower section presents the S&P 500-to-gold ratio, which measures how many ounces of gold are needed to buy the S&P 500 index. This ratio reveals a striking technical pattern: a massive head-and-shoulders formation, a bearish indicator in technical analysis that often signals a potential reversal. 

If this pattern completes, it could indicate a significant outperformance of gold over the S&P 500 in the coming years, potentially driven by a crisis that erodes confidence in equities while boosting demand for gold. 

Given gold’s historical predictive prowess for crises, as evidenced by its price surges before major economic and geopolitical upheavals, this head-and-shoulders pattern may well be fulfilled. 

____

References 

Prudent Investor Newsletter Oh, Gold!!!! February 23, 2020