Sunday, October 20, 2024

Melt-Up! Philippine Financial-Bank Index Hits a Milestone High!


Causa remota of any crisis is the expansion of credit and speculation while causa proxima is some incident that saps the confidence of the system and induces investors to sell commodities, stocks, real estate, bills of exchange, or promissory notes and increase their money holdings. The causa proxima may be trivial: a bankruptcy, a suicide, a flight, a revelation of fraud, a refusal of credit to some borrowers, or some change of view that leads a market participant with a large position to sell. Prices fall. Expectations are reversed. The downward price movement accelerates—Charles P. Kindelberger 

In this issue

Melt-Up! Philippine Financial-Bank Index Hits a Milestone High!

I. US Banks Powered Global Financials ETF to a Record High!

II. Melt-up! The Philippine Financial-Bank Index Carves a Fresh All-Time High!

III. Tightening, what Tightening? Finance Outperformed the PSE Since 2020, Banks Centralize Financial Resources

IV. The Paradox of Financial and Real-Estate Performance; Year-To-Date Performances of Listed Banks

V. Record Financial Index: From the Perspective of Volume and Foreign Money Flows

VI. Cross-Border Leveraged Speculation Powered the Record High of the Financial/Bank Index

VII. Bank Borrowings in a Melt-UP Phase too! Conclusion

Melt-Up! Philippine Financial-Bank Index Hits a Milestone High!

The share prices of many Philippine banks have been in a melt-up. But what’s been driving this surge?

I. US Banks Powered Global Financials ETF to a Record High!

Thanks to the extraordinary loosening of financial conditions, which has spurred booming credit and stock market activity, some of the top U.S. banks reported exceptional performance in Q3 2024 last week.

As a result, share prices of Morgan Stanley (NYSE: MS) and Goldman Sachs (NYSE: GS) soared to all-time highs.

In turn, BlackRock’s iShares Global Financials ETF, the IXG (NYSE ARCA: IXG), which has been on an uptrend since the lows of October 2020, also reached a fresh record high after surpassing its previous peak set in 2007.

The IXG's portfolio consists of 209 global equities primarily in financial services and banking, with over 55% of its holdings in US markets. This week, the IXG surged 2.25% and has generated a 26.13% return in 2024 (as of October 18).

Figure 1

Financials ranked fourth among the best-performing sectors in the S&P 500, with a 26.5% return, trailing Information Technology at 33.25%, Utilities at 29.3%, and Communications at 28.3% (as of October 18). [Figure 1, topmost table]

Despite the backdrop of supposedly high interest rates, October 2022 marked a turning point for the financial sector. This followed the Bank of England’s (BoE) intervention to rescue its troubled pension funds during the selloff of UK bonds.

The subsequent bailout of U.S. banks during the 2023 crisis further emboldened speculative activity, as central bank interventions have created what many view as a "moral hazard"—the belief that central banks will always step in to support the markets.

Expectations of easing by the Federal Reserve and other central banks have fueled the blistering rise of the IXG. The rapid pace of this ascent bears an unsettling resemblance to the 2007 episode, which preceded the Great Financial Crisis (GFC). [Figure 1, middle image]

II. Melt-up! The Philippine Financial-Bank Index Carves a Fresh All-Time High!

What does this have to do with the PSE?

The PSEi 30 closed the week ending October 18th up 1.44%, pushing 2024 Year-to-Date (YTD) returns to 14.97%.

Leading the gains this week was the Financial/Bank Index, with a 3.5% spike, followed by the Property Index, which climbed 2.11%.

The strong performance of the banking and property sectors supposedly reflects the Bangko Sentral ng Pilipinas' (BSP) announcement of its second round of rate cuts, effective October 17.

With this week’s surge, Financials have swiftly secured the second spot YTD with a 39.3% return, closing in on the ICT-led Service Sector, which holds the top position with 40.7%.

Since the PSEi 30 hit its June 2021 lows—mirroring trends in the U.S.—financials have sprinted ahead of other sectors. The Financial Index returned 29.9%, followed by the Property Index at 25%, both contributing to the PSEi 30’s overall 20.4% gain over this period. (Figure 1, lowest graph)


Figure 2

Here’s the thing: the Financial/Bank Index set a new record last September, surpassing its January 2018 high of 2,325.65. In a parabolic fashion, similar to global markets, the financial/bank index decisively reinforced its end-September breakout with this week’s push to 2,421.6. (Figure 2, topmost chart) 

Once again, China Bank’s incredible vertical rise is unprecedented, showcasing price volatility that is unbecoming of traditional banks. (Figure 2 middle chart) 

As previously pointed out, similar to the Lehman episode, skyrocketing prices tend to disguise underlying problems. 

In essence, the parabolic rise of financials hardly indicates a healthy bull market. If history serves as a guide (as seen in 2012 and 2018), this could be a sign of an interim top. 

Or could this time be different? 

III. Tightening, what Tightening? Finance Outperformed the PSE Since 2020, Banks Centralize Financial Resources 

The Financial/Bank Index currently consists of eight constituents: seven banks—Asia United Bank [AUB], BDO Unibank [BDO], Bank of the Philippine Islands [BPI], China Banking [CBC], Metrobank [MBT], Philippine National Bank [PNB], and Security Bank [SECB]—and one non-bank entity, the Philippine Stock Exchange [PSE].

Three of the bank members in the Financial Index are also part of the PSEi 30 composite, with two of them ranking among the top five.

While recent mainstream discussions have focused on how banks benefit from the liquidity injections via significant Reserve Requirement Ratio (RRR) cuts, and BSP rate cuts, the Financial Index has been outperforming the PSEi 30 since 2020. (Figure 2, lowest diagram) 

This trend began when the BSP implemented historic measures to support the industry, including quantitative easing (QE), rate cuts, RRR cuts, and relief measures.

This indicates that current dynamics represent a continuation of an underlying trend.

Figure 3

The BSP’s Total Resources of the Financial System (TRFS) data reveals that not only is it outgrowing GDP, but the share of banking resources—particularly from universal commercial (UC) banks—has been driving most of this growth. Philippine bank and UC bank share of the TRFS accounted for 83.4% and 78.05% last August. (Figure 3, topmost window) 

This highlights a concentration of resources and a deepening dependence of the economy on bank credit and liquidity. Thus, when officials claim they are promoting capital markets, it only holds true if banks benefit from it. 

Ironically, despite previous rate hikes, the TRFS suggests there has been little actual "tightening" or "restrictiveness" in the system. 

The outperformance of the Financial/Bank Index further confirms this. Yet, even with the availability of public data, discussions surrounding these insights are often sparse. 

IV. The Paradox of Financial and Real-Estate Performance; Year-To-Date Performances of Listed Banks 

In contrast, despite the substantial rebound in the Property Index from June 21 through September, it has yet to break its pattern of underperformance relative to the PSEi 30. (Figure 3, middle graph) 

These divergent trends suggest that, regardless of the measures undertaken by the BSP, the property sector remains hindered by internal challenges. 

In fact, contrary to most predictions, low interest rates have contributed to the real estate sector's struggles. As the BSP eased monetary policy over the past decade, the sector's value-added share of GDP fell to recent all-time lows—an indication of malinvestment. (Figure 3, lowest chart)


Figure 4 

Still, the Year-to-Date (YTD) performance of all listed banks, which has averaged a return of 27.08% as of October 18, has been skewed in favor of the banks that are part of the financial/bank index. (Figure 4, topmost image) 

Rocketing stock prices of Financial Index members AUB and CBC have delivered impressive YTD returns of 91.3% and 94.59%, respectively. (Figure 4, middle visual) 

Meanwhile, PSEi 30 mainstays BDO, BPI, and MBT produced returns of 25.7%, 37.9%, and 56.5%, respectively. SECB also saw a solid return of 36.5%. 

Have CBC and AUB struck a "gold mine" that the market has only recently discovered? 

V. Record Financial Index: From the Perspective of Volume and Foreign Money Flows 

Volume and foreign money flows offer another perspective.

Although the PSEi 30 briefly surged past 7,500 before retreating, trading volume remains relatively sluggish.  (Figure 4, lowest graph) 

But that’s only part of the story. 

What remains less known to many is that despite this overall lethargy, financials and banks have captured the bulk of the trading volume or a significant portion has been concentrated in financials and banks. 

The BSP and PSE have yet to release transaction data for August and September.

Figure 5 

However, using July data, the 7-month share of financials' volume relative to total market volume reached an all-time high of 23.7% in 2023. It has since retreated to 19.1% this year, the second-highest on record. That number, however, could reach a new high in October. (Figure 5, topmost image) 

As of October 18, the financial sector's share of gross trading volume had soared to 26.5% (and its share of mainboard volume to 29.6%). 

In other words, the financial/banking sector has absorbed about a quarter of the PSE's sluggish trading volume! That’s an astonishing level of concentration risk—Incredible! 

Given my limited access to sophisticated database organizing tools, I have only managed to tabulate foreign flows using October data, which is limited to the top five Financial Index members: AUB, BDO, BPI, CBC, and SECB. 

There is no question that these top five banks dominate the turnover share, accounting for 90.7% during the week leading up to October 18 and 84.8% for the entire month of October. 

VI. Cross-Border Leveraged Speculation Powered the Record High of the Financial/Bank Index 

But here are some additional insights: 

Net foreign inflows of Php 892.5 million for the top five banks represented 20.94% of the Php 4.261 billion total foreign inflows for October.

Notably, a substantial portion of this, accounting for 87.8% or Php 953.2 million, originated from last week alone, out of a total inflow of Php 1.086 billion.

In short, the recent surge to a record high in the Financial/Bank Index was largely driven by foreign capital, likely bolstered by the "national team" (such as the treasury departments of banks, Maharlika SWF and other financial corporations or OFCs?).

Stunning.

It’s looks likely that some of the foreign money chasing the U.S.-based IXG (iShares Global Financials ETF) rally has been positioning itself in emerging market banks like those in the Philippines. 

What we are witnessing appears to be unadulterated, leveraged speculative cross-border allocations, primarily focused on banks and, to a lesser extent, communications companies (telcos). [See returns of S&P 500 sector above] 

Further, the PSEi 30’s weekly breadth was overwhelmingly positive, with 19 of the 30 issues gaining and three remaining unchanged, averaging a 1.43% increase—almost mirroring the index’s actual weekly return of 1.44%. Two stocks, Meralco and Century Pacific Food (CNPF), hit all-time highs this week. (Figure 5, middle chart)

Weekly gains in the three banks contributed significantly to the PSEi 30’s performance. These banks accounted for 22.6% of the index, while the top five heavyweights—two of which are banks—commanded over half (50.83%) of the PSEi 30 as of October 18. (Figure 5, lowest pane) 

VII. Bank Borrowings in a Melt-UP Phase too! Conclusion

Before we conclude, as we await the PSE and the BSP to release September and Q3 data on individual banks and the overall banking system, it is noteworthy that some banks, such as PBCOM and PNB, have recently announced plans to raise funds through debt issuance in the capital markets.

Figure 6

It’s not just share prices that are surging—Philippine banks are also experiencing a sharp increase in borrowing—bonds and bills soared 32.3% in August. (Figure 6, topmost and middle graphs)

Why the rush to raise funds?

The answer lies in the ongoing deterioration of liquidity within the banking system, as indicated by declining cash-to-deposit and liquid-assets-to-deposit ratios. (Figure 6, lowest chart) 

The pressing question is: How will banks continue to fund the government under these conditions? The BSP’s response: Cut their Reserve Requirements, unleash liquidity! 

To wrap up, what you see in the media or mainstream discourse often doesn’t reflect the full picture. 


Sunday, October 13, 2024

Has the Philippine Government Won Its Battle Against Inflation? SWS Self-Poverty Survey Disagrees, Unveiling Its Hidden Messages


There is no escape from debt. Paying for the government’s fictitious promises in paper money will result in a constantly depreciating currency, thereby impoverishing those who earn a wage or have savings. Inflation is the hidden tax, and it is very convenient for governments because they always blame shops or businesses and present themselves as the solution by printing even more currency. Governments want more inflation to reduce the impact of the enormous debt and unfunded liabilities in real terms. They know they can’t tax you more, so they will tax you indirectly by destroying the purchasing power of the currency they issue—Daniel Lacalle

 In this issue

Has the Philippine Government Won Its Battle Against Inflation? SWS Self-Poverty Survey Disagrees, Unveiling Its Hidden Messages

I. Unveiling the Likely Hidden Messages Behind the Declaration of Victory Over Inflation

II. Treasury Curve was Spot On about Inflation, Short-Term Treasury Yields Plunge! Will the BSP Cut by 50 bps?

III. Supply-Side Disinflation? Despite Strong Credit Growth, Manufacturing Remains in the Doldrums, as Reflected by PPI Deflation and Output Sluggishness

IV. Supply-Side Disinflation? Lethargic Consumer Imports and July FDI Reflect Frail Capital Goods Imports

V. Demand-Side Disinflation? September CPI Plunged Despite Vigorous August Consumer Bank Lending, Liquidity Growth Dived

VI. Disinflation with Employment at Near Historic Highs Backed by a Credit Boom? Slower Deficit Spending Puts Pressure on Liquidity Strains

VII. SWS’s Self-Rated Poverty Survey versus the Government’s CPI 

Has the Philippine Government Won Its Battle Against Inflation? SWS Self-Poverty Survey Disagrees: Unveiling Its Hidden Messages

A Philippine media outlet proclaimed that the Philippine government won its battle against inflation, while a private survey contradicted this view. Who's right?

I. Unveiling the Likely Hidden Messages Behind the Declaration of Victory Over Inflation

Figure 1 

Two interesting headlines that hallmark this week’s conflicting message on inflation. 

Inquirer.net, October 7, 2024: The Philippines may now declare victory in its long and painful fight against inflation after price growth last month eased to a four-year low, helping create the perfect economic condition for gradual interest rate cuts…The BSP is now at a point where it has to undo its most forceful tightening actions in two decades, which had sent the benchmark rate to its highest level in 17 years to tame stubbornly high inflation. Cutting borrowing costs is necessary amid market predictions that the economy may grow below the government’s target for this year after consumption showed signs of weakening…Moving forward, Governor Eli Remolona Jr. said the central bank would take “baby steps” until the key rate falls to 4.5 percent by the end of 2025, suggesting that monetary authorities would unlikely resort to jumbo cuts that may stir up market fears that the economy is headed for a hard landing. (bold mine)

SWS.org.ph, October 9, 2024: The national Social Weather Survey of September 14-23, 2024, found 59% of Filipino families rating themselves as Mahirap or Poor, 13% rating themselves as Borderline (by placing themselves on a line dividing Poor and Not Poor), and 28% rating themselves as Hindi Mahirap or Not Poor. The September 2024 percentage of Self-Rated Poor families rose by 1 point from 58% in June 2024, following a significant 12-point rise from 46% in March 2024. This was the highest percentage of Self-Rated Poor families since June 2008. The estimated numbers of Self-Rated Poor families were 16.3 million in September 2024 and 16.0 million in June 2024. The percentage of respondent households rating themselves as poor was applied to the Philippine Statistics Authority medium-population projections for 2024 to arrive at the estimated numbers of Self-Rated Poor families… The September 2024 survey found the percentage of Borderline families at 13%, up by 1 point from the record low 12% in June 2024 following an 18-point decline from 30% in March 2024… As of September 2024, the percentage of Not Poor families was at 28%, 2 points below the record high 30% in June 2024. (bold mine)

First and foremost, what does "declare victory in its long and painful fight against inflation" mean? (Figure 1, upper tweet)

The Philippine CPI posted two straight months of DEFLATION (statistical price decreases) in September (-0.37%) and October (-0.19%) 2015; yet, the media and establishment experts barely made such a brazen pronouncement until now.

Yes, Q3 2024 statistical inflation of 3.2% has dropped to its 9-year support level, but this doesn’t mean that the inflation cycle has been broken.


Figure 2
 

In Q3 2015, the CPI slipped into deflation at -0.1%, which prompted banks to accelerate their net claims on central government (NCoCG) or indirect QE. Ironically, this germinated the current inflation cycle, which is now on its ninth-year.  (Figure 2 upper image)

Despite its recent decline, given that the CPI has remained on an uptrend since 2015 and appears to have settled at the support levels, what assurances does the establishment hold that it won’t be subject to a third wave?

Second, the September CPI of 1.9% doesn’t translate to the evisceration of inflation; it only means that GENERAL prices have risen at REDUCED rates (or have dropped to within the BSP’s target), but they are still RISING!

In fact, BSP data tell us that even in the context of the understated inflation rate, over 99% of the purchasing power of the peso has been eroded since 1957! How is that for "declaring victory over inflation"? (Figure 2, lower chart)

On the other hand, while authorities and media bask in this pretentious statistical feat, a private sector survey tell us a different story: slower inflation has exposed the persistent and growing burden of a lower standard of living! (More on this below.) (Figure 1, lower tweet)

Third, "declaring victory over inflation" was NEVER a goal of the BSP’s monetary policy anchored on inflation targeting.

From the BSP: The primary objective of the BSP's monetary policy is “to promote price stability conducive to a balanced and sustainable growth of the economy” (Republic Act 7653). The adoption of inflation targeting framework of monetary policy in January 2002 is aimed at achieving this objective. Inflation targeting is focused mainly on achieving a low and stable inflation, supportive of the economy’s growth objective. This approach entails the announcement of an explicit inflation target that the BSP promises to achieve over a given time period. (bold mine)

There is no defined quantification or qualification of "low and stable inflation" because statistical inflation has always been a subjective measure, arbitrarily defined by the BSP.

That said, the goal of the politics behind inflation targeting has been to keep the inflation "genie" confined within the boundaries of the BSP’s proverbial "lamp."

That’s because inflation, as a hidden tax, benefits the government most.

However, the inflation genie has been set loose, or has gone beyond its bounds, marking the difference between the previous era and today.

In this way, the BSP can be conservatively said to have been "asleep at the wheel."

At worst, and unbeknownst to the public, the BSP’s policies have unleashed the inflation genie!

Or, although authorities continue to push the narrative of supply-side-driven inflation to shift the blame onto the private sector, the current inflation cycle signify an unintended consequence of their policies!

Yet, has anyone among the array of establishment experts, including those in government, been correct in predicting the incumbent inflation cycle? 

Fourth, the CPI is just a statistic. While its intent is to approximate changes in general prices, it neither reveals the full accuracy nor explains the causes of those changes. 

The fact is that inflation statistics are misleading.

My inflation rate and yours are different.  This is because of dynamic individual spending habits and ever-changing preferences that vary not only over time but also differs across individuals. 

Is it not the averaging a Netflix subscription and rice an exercise of apples-to-oranges comparison?  If so, would this not be applied to the CPI? 

Or, not only is the weighted averaging of goods and services across different groups of people a flawed metric, but people’s spending preferences are constantly changing! 

How accurate is an inflation rate derived from averaging the spending patterns of billionaires with those of the bottom 30%? 

Even on a personal level, my preferences are always changing. If I prefer sautéed prawns with bread this moment, adobo with rice later, and only sinigang for tomorrow, how could the inputs used to create these meals be accurately averaged? How would this apply to a population of 110 million people? 

Furthermore, because the CPI is a politically sensitive statistic—created and calculated by politically sensitive institutions—it is prone not only to errors (in assumptions, inputs, etc.) but also to political biases. 

For instance, changing the base year of the CPI can lead to different outcomes. If I’m not mistaken, using the now-defunct 2006 base would produce a much higher CPI today than the current 2018 base. 

Since the CPI is used as a primary benchmark for the market’s pricing of interest rates, wouldn’t the government—as the biggest borrowers—have the incentive or motivation to suppress it to influence the cost of borrowing? 

Fifth, what happened to journalism? 

Isn’t journalism about "seeking truth and providing a fair and comprehensive account of events and issues"? 

When media outlets use ambiguous qualifications like " declare victory against inflation" to describe the "perfect economic condition for gradual interest rate cuts" intended to support "consumption (which) showed signs of weakening," could this not signify cheerleading or an advocacy for a biased policy stance? For whose benefit? 

Might this be seen as advancing the interests of vested groups, particularly the primary beneficiary, the government and the politically connected elites? How is this different from propaganda, misinformation, or disinformation? 

Importantly, if an alleged news article makes an economic generalization, why would it lack narratives supported by economic logic? 

Or, are low rates a GUARANTEE of an INCREASE in consumption? How so, and based on what theory and evidence? 

Why cite partisan and non-sequitur explanations from "establishment experts" whose principal-agent problems have hardly been laid bare to the public? 

Have media outlets distilled such insights or selected statements for print that only promote their biases? I’ve seen this happen (personally) before, which is why I refuse interviews. 

Sixth, if media pronouncements reflect exuded marketplace confidence, could such article/s signify a manifestation of the magazine/headline cover indicator or express an extreme state of sentiment? 

Or have the media’s declarations echoed the "overconfidence" stemming from recent euphoria over the price spikes in Philippine assets (stocks, bonds, and the peso)? 

Seventh and lastly, could this be related to the upcoming elections? 

Will declaring 'victory in its long and painful fight against inflation' be part of the campaign to promote the electoral chances of the administration’s national slate in the 2025 midterm elections? 

Ultimately, the establishment's obsession has been to promote a regime of easy money, using the declaration of triumph over inflation as justification. 

As the great Austrian economist Ludwig von Mises once explained 

The popularity of inflation and credit expansion, the ultimate source of the repeated attempts to render people prosperous by credit expansion, and thus the cause of the cyclical fluctuations of business, manifests itself clearly in the customary terminology. The boom is called good business, prosperity, and upswing. Its unavoidable aftermath, the readjustment of conditions to the real data of the market, is called crisis, slump, bad business, depression. People rebel against the insight that the disturbing element is to be seen in the malinvestment and the overconsumption of the boom period and that such an artificially induced boom is doomed. They are looking for the philosophers' stone to make it last (Mises, 2019)  

II. Treasury Curve was Spot On about Inflation, Short-Term Treasury Yields Plunge! Will the BSP Cut by 50 bps? 

While the headline CPI plummeted from 3.3% in August to 1.9% in September—its lowest monthly rate since May 2020—excluding food and energy, the core CPI slipped to 2.4%, signifying 17 of 18 months of decline (one unchanged) since peaking at 8% in March 2023. 

Before that, we showed how changes in the Philippine yield curve have accurately predicted the CPI slump. 

despite the 4.4% CPI bump in July (and Q2 6.3% GDP), the Philippine treasury market continues to defy inflationary expectations by maintaining a deep inversion of the curve’s belly, which again signals slower inflation, upcoming BSP cuts, and increased financial and economic uncertainty. (Prudent Investor, August 2024) 

… 

Moreover, the curious take is that despite all the massive stimulus, the belly’s inversion in the Philippine treasury market has only deepened at the close of August.  

This does not suggest a build-up of price pressures or a strong rebound in the private sector. On the other hand, rising short-term rates indicate intensifying liquidity issues.   

In the end, while Marcos-nomics stimulus seems to have reaccelerated liquidity, a resurgence of inflation is likely to exacerbate "stagflationary" pressures and increase the likelihood of a bust in the Philippines’ credit bubble. (Prudent Investor, September 2024) 

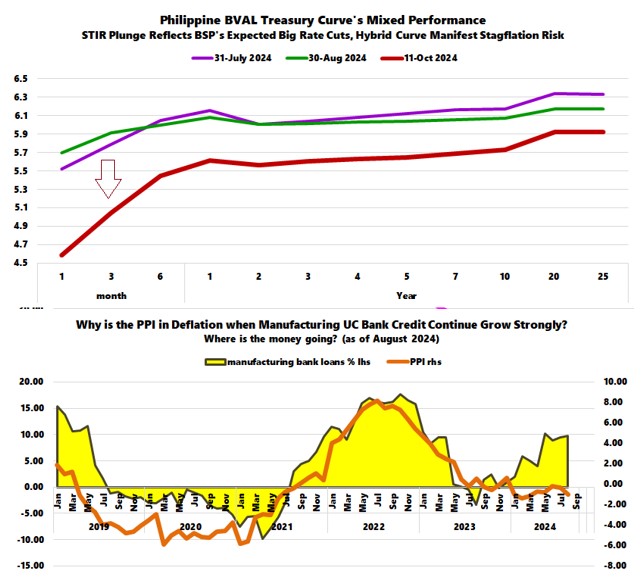
Volatility has crescendoed in the Philippine treasury curve.


Figure 3

The present slope exhibits an astounding collapse in short-term rates (STIR), manifesting institutional market expectations of substantial cuts in BSP rates. Will the BSP cut by 50 bps this October? (Figure 3, upper graph) 

Yet, the curve’s magnified volatility has been incredible: following the gradual transition from flat to an inverted curve, then swiftly to a bullish steepening, and next to the current abrupt regression to a partial belly inversion—even with the plunge in STIR—how could this not be conducive to the rising risks of stagflation?

III. Supply-Side Disinflation? Despite Strong Credit Growth, Manufacturing Remains in the Doldrums, as Reflected by PPI Deflation and Output Sluggishness 

While we perceive government statistics with cynicism, we still use them because almost every financial market participant does.

Instead of focusing on the potential factors for the drop, the mainstream fixates on the prospective policy easing by the BSP.

Could the plunge in inflation have been a supply-side phenomenon marked by a glut?

In a word: Barely.

Manufacturing value grew by 2.9% in June, 6.45% in July, and 1.78% in August, while volume was up by 3.2%, 6.9%, and 2.8% over the same period.

Meanwhile, despite strong Universal Commercial Bank (UCB) loan growth to this sector—rising by 8.9%, 9.5%, and 9.8%—the Producer Price Index (PPI) deflated by -0.2%, -0.4%, and -1%. (Figure 3, lower chart)

Here’s the question: Why has robust credit growth not been reflected in output performance?

Worse yet, why is the deflation in the PPI escalating? PPI defined by the Philippine Statistics Authority, "measures the average change over time in the prices of products or commodities produced by domestic manufactures and sold at factory gate prices."

Where has all the credit money generated gone?

Has it been diverted to real estate or other undeclared allocations? Or has it been used for refinancing existing liabilities?

IV. Supply-Side Disinflation? Lethargic Consumer Imports and July FDI Reflect Frail Capital Goods Imports

If manufacturing growth has been unimpressive or sluggish, the situation is even worse for imports.

Imports in USD posted a 7.3% YoY contraction in June, then rose by 7.3% in July and 1.8% in August.

Converted to average pesos, imports were down by 2.63% YoY in June, surged by 14.3% in July, and grew by 4.6% in August, with the last month’s growth reflecting revaluation effects from a strong peso.


Figure 4

Here’s the thing: Consumer goods USD imports contracted by 7.3% in June, increased by 3.1% in July, and remained unchanged in August. (Figure 4, topmost pane)

Meanwhile, capital goods imports shrank by 8.8% in June but surged by 9.5% and 9.6% in the next two months. A substantial segment of the YoY changes reflects base effects. (Figure 4, middle diagram)

Nonetheless, the growth in capital goods imports partly reflected foreign direct investment (FDI).

The prosaic July FDI growth of 5.5% YoY (7.5% year-to-date) resonated with mediocre import growth. (Figure 4, lowest graph)

Yet, debt accounted for 74.3% of total FDI inflows and 63.5% of year-to-date FDI inflows. How much of this represent actual investments?

Still, why is the growth rate of FDIs declining?

Importantly, where are the investment pledges from the US-NATO allies?

V. Demand-Side Disinflation? September CPI Plunged Despite Vigorous August Consumer Bank Lending, Liquidity Growth Dived

Was the CPI slump a function of demand?

In short, yes!

We should put into context the seismic transformation of the Philippine banking system, with its recent focus on consumer loans coming at the expense of the supply side.

Figure 5

Universal Commercial (UC) bank consumer lending slowed from 24.3% year-over-year (YoY) in July to 23.7% in August, marking its slowest pace since November 2023. (Figure 5, topmost chart)

Consumer loan growth was strong across all segments in August: credit cards +27.44%, auto loans +19.3%, salary loans +16.4%, and others +26.8%.

Meanwhile, production loans continue to accelerate, expanding from 8.8% in July to 9.4% YoY in August, primarily in the real estate and trade sectors.

Overall, UC bank lending grew from 10.4% to 10.9% in August (Figure 4, second to the highest graph)

Despite mainstream claims of "restrictiveness" or "tightness" due to elevated rates, UC Bank's loan growth has been on an uptrend. Still, the CPI continues its downward trajectory!

Worse yet, despite this, financial liquidity plummeted in August.

M3 growth, which was 7.3% in July, dived to 5.5% in August. Incredible.

Incidentally, the yield curve inversion reflected this!

Once again, what happened to all the record money creation by the banking system and the BSP? Why the black hole?

VI. Disinflation with Employment at Near Historic Highs Backed by a Credit Boom? Slower Deficit Spending Puts Pressure on Liquidity Strains

Why could this be happening when employment rates are near all-time highs?

It was 96% last August, only a smidgen lower than the 96.9% record set last December 2023. (Figure 5, second to the lowest window)

Could it be that, aside from trade, government jobs were the primary source of growth in August? (Figure 5, lowest image)

Or could it also have been that employment growth has been mostly about low-quality labor? Alternatively, could the employment data also have been embellished?


Figure 6

Moreover, as we previously noted, because Philippine public spending has slowed, the fiscal deficit slightly "narrowed" year-to-date (YTD) as of August. Public spending has tracked the CPI over the long-term. (Figure 6, topmost diagram) 

As a result, aided by the strong peso, public debt marginally weakened in August.

Moreover, has the stalling growth in system leverage (UC bank credit + public debt) contributed to the demand pressures reflected in the CPI? (Figure 6, second to the highest graph)

Consequently, net claims on the central government (NCoCG) by banks and the BSP plateaued or consolidated. (Figure 6, second to the lowest chart)

Or, aside from the BSP, liquidity injections channeled through banks have slowed slightly.

This, combined with a stealth rise in bank non-performing loans (NPLs) and elevated levels of held-to-maturity assets (HTMs), has contributed to the liquidity squeeze.

And this has occurred despite the record nominal bank credit expansion and historically high employment rates. The plunge in September’s CPI might reflect a downturn in public and private demand, possibly worsened by mounting signs of a liquidity shortfall.

VII. SWS’s Self-Rated Poverty Survey versus the Government’s CPI 

Things don’t happen in a vacuum.

The BSP suddenly announced a massive reduction of the banking system’s reserve requirement ratio (RRR) on September 20th, obviously in response to such developments. The adjustment takes effect on October 25.

The PSA’s September CPI data exhibits a broad-based decline in price growth. While food prices had the biggest influence on the CPI’s significant downside volatility, slowing aggregate demand reflected the diminishing pace of price increases across most sectors. (Figure 6, lowest image)

All these factors point to the SWS Q3 data indicating an increase in self-rated poverty, which not only highlights the decline in living standards for a significant majority of families but also emphasizes the widening gap between the haves and the have-nots.

As a caveat, survey-based statistics are vulnerable to errors and biases; the SWS is no exception.

Though the proclivity to massage data for political goals is higher for the government, we can’t discount its influence on private sector pollsters either.

In any case, we suspect that a phone call from the office of the political higher-ups may compel conflicting surveys to align as one.

____

References 

Ludwig von Mises, The Boom Is Worse than the Bust, November 30, 2018 Mises.org 

Prudent Investor, The Philippines' July 4.4% CPI: Stagflation Remains a Primary Political, Economic, and Financial Risk August 12, 2024


Prudent Investor, Philippine Government’s July Deficit "Narrowed" from Changes in VAT Reporting Schedule, Raised USD 2.5 Billion Plus $500 Million Climate Financing September 1, 2024


Monday, October 07, 2024

Important Insights from the Philippine PSEi 30’s Melt-Up!


Investors believe in Keynesianism.  They believe that increased government spending will make us all richer.  This illusion is what is driving this stock market. Bubbles are based on illusions—Dr. Gary North 

In this issue

Important Insights from the Philippine PSEi 30’s Melt-Up!

I. Philippine PSEi 30 Returns Among the World’s Highest

II. Lessons from China’s Previous Easy Money Experiments

III. Market Concentration and Unimpressive Volume and Breadth, Rampaging Philippine Bank Shares and the Lehman-Bear Stearns Experience

IV. Retail Players Emerge

V. Why the Opposite Direction of San Miguel’s Share Prices? Conclusion

Important Insights from the Philippine PSEi 30’s Melt-Up!

What does the outperformance of the PSEi 30 likely mean?

I. Philippine PSEi 30 Returns Among the World’s Highest

The Philippines' primary equity benchmark, the PSEi 30, stretched its weekly winning streak to five with this week’s 0.53% gain.

This week’s gains pushed its year-to-date returns to 15.8% (as of October 4th).


Figure 1

Accompanied by a massive rally in the Philippine peso, the Philippines' ETF, the EPHE, joins the ranks of global top equity ETFs in terms of US dollar returns (as of October 2nd). (Figure 1, upper window)

Year to date, the PSEi 30 ranked fourth in Asia, after Pakistan, Hong Kong, and Taiwan. (Figure 1, lower image) 

With 16 of the 19 regional benchmarks up by an average of 13.13% in local currency terms, we can generalize that 2024 has been a year of the bulls. Of course, we have two more months to go.

II. Lessons from China’s Previous Easy Money Experiments

Despite recent elevated rates, the current surge in global stocks signifies a product of easy money.

Due to the massive coordinated bailout package unleashed by Chinese authorities to rescue its struggling asset markets (stocks and real estate), Chinese and Hong Kong equities skyrocketed, rising by a stunning 23.4% and 31% over the last four weeks.

However, the returns of China’s equity markets have been capped due to a week-long holiday.

Figure 2

Though many international experts have suddenly become apostates to a perceived return of China’s bull market, I recently pointed out in a tweet that... (Figure 2)

"While previous episodes of government stimulus did bolster valuations, they turned out to be short-lived, highly volatile, and resulted in diminishing returns for #SSE levels. The 2016 & 2020 support had little impact on its bear market. Will history rhyme?"

Or whatever boom that took place before tended to morph into a bust. Even worse, the subsequent stimulus produced diminishing returns with the lower levels of the Shanghai Composite Index (SSE).

In other words, monetary inflation or stimulus from credit expansion must be applied at a much larger scale than before to magnify the effects of a boom. 

As the great Dean of Austrian economics, Murray Rothbard, once warned 

Like the repeated doping of a horse, the boom is kept on its way and ahead of its inevitable comeuppance by repeated and accelerating doses of the stimulant of bank credit. It is only when bank credit expansion must finally stop or sharply slow down, either because the banks are getting shaky or because the public is getting restive at the continuing inflation, that retribution finally catches up with the boom. (Rothbard, 2015)

China’s experience has somewhat resonated with the Philippines.

Figure 3

It took a combination of historic rate cuts, massive reductions in reserve requirements, unprecedented relief measures, and direct injections by the BSP into the banking system via the expansion of its balance sheet to rescue the Philippine PSEi 30 in 2020. (Figure 3, upper image) 

The PSEi 30 peaked in 2022 along with the cresting of the BSP's assets. 

It is also not a coincidence that the PSEi has wilted in the face of the slow-motion erosion of the BSP’s balance sheet, which was eventually reversed in 2023. 

The BSP’s U-turn put a floor under the PSEi 30 and rebooted the current rally. 

One can probably thank Other Financial Institutions (OFCs) for representing part of the National Team supporting the PSEi 30. 

The BSP has been rebuilding its asset base, this time from external borrowings by the National Government and the banking system. 

III. Market Concentration and Unimpressive Volume and Breadth, Rampaging Philippine Bank Shares and the Lehman-Bear Stearns Experience 

Of course, the difference between the bull market of 2009-2013 and today is that the PSEi 30 run has barely been supported by volume and breadth. 

Main board volume remains substantially below the level reached at even lower PSEi 30 levels in 2022. (Figure 3, lower graph) 

Because of this obsession with pumping the index to portray a bull market, the "national team" has concentrated its aggressive stock-pumping activities on the top heavyweights. 

As a result, the market capitalization share of the top five companies reached 51.1% last October 4, following a record 51.92% last April.

Figure 4

Furthermore, because RRR cuts and BSP rate cuts were sold to the public as policies that would accomplish economic nirvana, the Financial/Banking Index roared, with year-to-date returns spiking 37.7% and its index soaring to a record high! (Figure 4, upper chart) 

Astoundingly, shares of China Bank [PSE:CBC] have spiraled in ways echoing Bitcoin, GameStop [NYSE:GME], and Nvidia [Nasdaq:NVDA]! (Figure 4, lower pane)

CBC posted 91.3% year-to-date returns, with much of that accomplished in the last four weeks!

Figure 5

If history tells us anything, bank share prices going berserk could mean anything other than economic or financial prosperity. The experiences of Lehman Brothers and Bear Stearns provide examples: their share prices sprinted to an all-time high before collapsing, heralding the Great Financial Crisis (2007-2008). (Figure 5, topmost chart)

To be clear, we aren’t suggesting that CBC and other record-setting bank shares, such as BPI, are a simulacrum of Lehman; rather, we are pointing to the distortive behavior of speculative derbies that may hide impending problems in the sector. 

Of course, foreign buying did provide support to the national team. For the first time since 2019, the PSE posted net inflows of Php 108 million in the first nine months of 2024. (Figure 5, middle graph)

Meanwhile, in the PSE, the cumulative market share of the PSEi 30’s best-performing ICT and the three PSEi 30 banks has reached 32.73%, which is closing in on August's record of 33.14%.  

IV. Retail Players Emerge 

However, signs indicate that the retail segment appears to be jumping on board the developing mania, which has been marketed as another version of the "return of the bull market." 

Though still negative, 2024’s nine-month breadth has had the best showing since 2017. (Figure 5, lowest image)

Figure 6

Furthermore, the declining share of the top 10 brokers relative to the MBV could be another contributing factor. It was 60.4% in the week of October 4th, down from a recent high of over 65%. (Figure 6 upper visual) 

Major brokers could utilize 'done-through' trades or outsource trades with partner brokers to conceal or dilute this number.

Despite the paucity of volume, the trading share of the top 20 most-traded issues has dropped to about 80% for the fourth consecutive week from the previous range of 84-86%. (Figure 6, lower diagram)

Figure 7

Since the low on June 21st, the returns of the top 10 heavyweights delivered the bulk of the gains for the PSEi 30. While 23 issues closed higher, 2 remained unchanged, and 5 declined. The average return of the top 5 was 26.84%, while the average return for the top 10 was 26.4% (Figure 7, topmost graph) 

Breadth was largely incongruent with this week’s 0.53% returns, 83% of which were attributable to Friday’s pre-closing pump. Although 18 of the composite PSEi 30 issues closed down, the upside volatility allowed for a positive weekly return of 0.21% (Figure 7, middle image) 

V. Why the Opposite Direction of San Miguel’s Share Prices? Conclusion 

Finally, SMC share prices continue to move diametrically opposite to the sizzling hot PSEi 30. (Figure 7, lowest graph) 

What gives? Will SMC’s debt breach the Php 1.5 trillion barrier in Q3?   

Have SMC’s larger shareholders been pricing in developing liquidity concerns? If so, why are bank shares skyrocketing, when some of them are SMC’s biggest creditors? 

Bottom line: The levels reached by the PSEi 30 and its outsized returns attained over a few months barely support general market activities, which remain heavily concentrated on the actions of the national team and volatile foreign fund flows. 

Instead, the present melt-up represents an onrush of speculative fervor driven by the BSP’s stealth liquidity easing measures, even before their rate cut. Moreover, real economic activities hardly support this melt-up.

___

reference 

Murray N. Rothbard, Why the Recurring Economic Crises?, August 27, 2015, Mises.org